
 “The Crux of it” blog
Transferable tax credits: The complete 2026 guide for buyers and sellers


Transferable tax credits are federal energy and manufacturing tax credits that can be sold for cash to another taxpayer. Sellers, including developers, manufacturers, and clean energy project sponsors, turn tax credits they cannot use into capital for new projects. Buyers reduce their federal income tax bill by purchasing the tax credits at a discount.
Congress created this option in 2022 under Section 6418 of the Internal Revenue Code. Since then, the market has grown into one of the largest sources of financing for US energy and manufacturing projects: tax credit transfer volume reached $42.0 billion in 2025, and Crux expects $47.5–49.0 billion in 2026.
This guide explains how tax credit transfers work, what has changed in 2026, and what buyers and sellers need to know to transact with confidence.
Go deeper: Understand trends in the tax credit market in H1 2026.
General transferable tax credit FAQs
What are transferable tax credits?
Transferable tax credits are federal tax credits that an eligible taxpayer can sell, once, to an unrelated taxpayer for cash under Section 6418. The buyer applies the purchased tax credit against its federal income tax liability. The seller receives cash without forming a partnership with the buyer or giving up ownership of the project.
Transferability sits alongside tax equity as a second way to monetize clean energy and manufacturing tax credits. It has three main advantages:
- It brings more capital to energy and manufacturing infrastructure by opening the market to any corporate taxpayer, not only the large financial institutions that dominate tax equity.
- It broadens access to capital for mid-size developers, manufacturers, and fuel producers that historically could not attract tax equity.
- It supports a wider range of technologies, including storage, nuclear, clean fuels, and advanced manufacturing.
How does a tax credit transfer work?
A tax credit transfer moves through five steps. The seller earns the tax credit, registers it with the Internal Revenue Service (IRS), signs an agreement with a buyer, and both parties report the transfer on their tax returns.
- The seller earns the tax credit. An investment tax credit (ITC) is earned when the project is placed in service. A production tax credit (PTC) is earned as the facility produces and sells electricity, fuel, or components.
- The seller completes IRS pre-filing registration. The seller registers each eligible project through the IRS online portal and receives a registration number for each one. The IRS recommends allowing 120 days for processing.
- The buyer and seller sign a tax credit transfer agreement. The agreement sets the price, payment timing, representations, and indemnities. Deals are often signed and funded before the registration number arrives, so the transaction and registration run in parallel.
- Both parties sign a transfer election statement. This statement identifies the tax credits, includes the registration number, and confirms the seller provided the documentation the regulations require. Once filed, the election cannot be revoked.
- Both parties file their tax returns. The seller and buyer each attach the transfer election statement to their returns, filed by the due date including extensions. The seller reports the transfer on IRS Form 3800, and the buyer claims the tax credit.
Buyers do not have to wait until the transfer is complete to benefit. US Department of the Treasury guidance allows a buyer to count tax credits it has purchased, or intends to purchase, when it calculates its quarterly estimated tax payments.
How are transferred tax credits taxed?
Neither side pays federal income tax on the transaction itself. Section 6418 and the final regulations set three rules:
- The seller does not pay tax on the sale proceeds. Cash received for transferred tax credits is excluded from the seller's gross income. When a partnership sells, the proceeds are treated as tax-exempt income and flow to partners the same way the tax credits would have.
- The buyer cannot deduct the purchase price. The payment is not a business expense.
- The buyer does not pay tax on the discount. If a buyer pays $93 million for $100 million of tax credits, the $7 million difference is not treated as income.
Corporate buyers should also check how purchased tax credits interact with the corporate alternative minimum tax, the base erosion and anti-abuse tax (BEAT), the global minimum tax under Pillar Two, and financial accounting rules.
What rules apply to every tax credit transfer?
Section 6418 keeps the transfer process simple, but every transaction must follow a few firm rules:
- Cash only. Buyers must pay in cash, such as a wire or ACH transfer. Discounts on services or other in-kind value can invalidate the transfer.
- One transfer only. A buyer cannot resell tax credits it purchased. Unused tax credits can be carried backward or forward instead.
- Unrelated parties only. The buyer cannot be related to the seller under the tax code's related-party definitions.
- Partial sales are allowed. A seller can sell all or part of a tax credit, and can split one project's tax credits among several buyers.
- Partnerships and S corporations sell at the entity level. The entity makes the transfer election.
- Lessees in a pass-through lease cannot transfer. The lessor in a sale-leaseback can.
- Some foreign buyers are excluded. For tax years beginning after July 4, 2025, tax credits subject to the new prohibited foreign entity (PFE) rules cannot be sold to a specified foreign entity. Legacy §45 and §48 tax credits are not affected.
Tax-exempt organizations, state and local governments, and rural electric cooperatives generally cannot sell tax credits this way. Most of them can instead claim cash directly from the IRS through elective pay under Section 6417.
How big is the transferable tax credit market?
Tax credit transfers totaled $42.0 billion in 2025, up from $28 billion in 2024, and Crux forecasts $47.5–49.0 billion in 2026. The market now includes thousands of buyers, developers, manufacturers, and intermediaries.
Three trends defined the first half of 2026:
- A record second quarter. Q2 2026 transfer volume reached $14.9 billion, the highest quarterly total Crux has recorded.
- PFE risk became the main driver of price. Whether a tax credit was subject to PFE rules explained more of the variation in H1 2026 pricing than deal size or seller credit rating, the factors that historically mattered most. Buyers favored tax credits with the least PFE exposure, so §45U nuclear PTCs and multi-credit portfolios sold at the top of the market.
- The technology mix shifted. Solar and wind, which face the heaviest PFE and permitting headwinds, lost market share: solar fell from 35.0% in 2025 to 30.0%, and wind from 23.0% to 7.5%. Battery storage and §45Z clean fuel tax credits filled the gap.
Corporate participation keeps widening: 21% of Fortune 1000 companies now participate in the tax credit market as tax credits become a standard, repeatable aspect of corporate tax planning.
Read more: Key takeaways from the state of clean energy finance in H1 2026.
Which federal tax credits are transferable?
Eleven federal tax credits can be transferred. They cover electricity generation, storage, manufacturing, clean fuels, carbon capture, and hydrogen. The One Big Beautiful Bill (OBBB) changed deadlines and added foreign-entity rules for several of them.
The type of tax credit impacts the risks associated with the transfer. ITCs are claimed once, when a project is placed in service, and can be recaptured if the project stops qualifying within five years. PTCs are earned as a facility produces and generally carry no recapture risk.
How did the OBBB change transferable tax credits?
The OBBB, signed July 4, 2025, kept transferability in place but changed which projects qualify and added PFE rules. These are the changes that matter most for buyers and sellers:
- Earlier deadlines for wind and solar. Wind and solar projects claiming §48E or §45Y must have begun construction by July 4, 2026, or be placed in service by the end of 2027. Crux estimates more than 170 GW of capacity was safe-harbored ahead of that date.
- New end dates for other tax credits. The §45V hydrogen tax credit now requires construction to begin before 2028, Section 45X wind components must be sold before 2028, and §45Z clean fuels was extended through 2029.
- PFE rules. Sections 48E, 45Y, 45X, 45U, 45Z, and 45Q now carry restrictions on ownership, effective control, and material assistance tied to specified foreign entities including China, Russia, North Korea, and Iran. Legacy §45 and §48 tax credits are exempt.
- A limit on foreign buyers. Tax credits subject to the PFE rules cannot be transferred to a specified foreign entity.
Treasury and the IRS issued the first PFE guidance, Notice 2026-15, on Feb. 12, 2026. It created safe harbors for the material assistance test, but ownership and effective control questions remain open.
PFE exposure is now the biggest single driver of tax credit pricing. In H1 2026, tax credits not subject to PFE rules sold at a premium of $0.015 for ITCs and $0.020 for PTCs. PFE-exposed deals made up about 20% of the market, just under $4 billion.
Go deeper: Crux's PFE resource hub.
Why did Congress create tax credit transferability provisions?
Before 2022, most developers could only capture the full value of clean energy tax credits through tax equity, a partnership in which an investor puts capital into a project in exchange for tax credits, depreciation, and cash. Tax equity is complex to structure and monitor, so a small group of large banks supplied most of it, mainly for large wind and solar projects with experienced sponsors. Smaller developers, manufacturers, and newer technologies were often left out.
Transferability fixed that bottleneck in two ways:
- More sellers can raise capital. Any eligible project can sell its tax credits through a direct agreement, without forming a partnership. That opened financing to storage, nuclear, geothermal, clean fuels, and domestic manufacturing.
- More buyers can participate. Any corporate taxpayer can buy tax credits without the accounting and oversight burden of a tax equity investment, which multiplies the capital available.
The timing matters. US electricity demand is rising for the first time in decades, driven by data centers, artificial intelligence, and domestic manufacturing. Transferability helps finance the generation, storage, and supply chains needed to keep power reliable and affordable. Tax equity remains an important complement, especially in hybrid structures.
Who is involved in a tax credit transfer?
- Sellers: Developers, independent power producers, manufacturers, fuel producers, and project sponsors that earn tax credits.
- Buyers: Corporations, and in some cases individuals, with federal income tax liability.
- Tax advisors and syndicators: Firms that help clients discover, structure, and execute tax credit transfers.
- Legal and tax counsel: Lawyers and accountants who review the project, draft the transfer agreement, and issue tax opinions.
- Insurers: Tax credit insurers that protect buyers if the IRS later disallows or recaptures tax credits.
What role does Crux play in a tax credit transfer?
As part of its solutions across the full capital stack, Crux manages tax credit transfers for both buyers and sellers, backed by market intelligence from roughly $85 billion in transactions.
For sellers. Developers, sponsors, and manufacturers can hand off the entire sale. Crux manages the placement from start to funding:
- Pricing strategy based on Crux’s proprietary transaction data.
- Buyer selection based on each buyer’s tax capacity, timing, and tax credit preferences.
- Negotiations, diligence, insurance, and documentation through funding.
- Coordination with any debt or tax equity raised at the same time.
Smaller tax credits, below the size of a managed placement, can be sold through Crux’s platform.
For buyers. Corporate buyers get hands-on support from the first conversation to funding. Crux starts by defining the buyer’s tax capacity, risk tolerance, timing, and the types of tax credits that fit its strategy, then builds a sourcing and diligence plan around those requirements:
- Market and pricing intelligence to set expectations.
- Guidance on tax credit selection.
- Counterparty vetting, including adverse-media review, plus diligence coordination.
- Process management through funding, alongside the buyer’s own legal and tax advisors.
Whether you are buying tax credits or selling tax credits, our team can help you transact with confidence.
Key section takeaways
- Section 6418 lets an eligible taxpayer sell federal energy and manufacturing tax credits once, for cash, to an unrelated buyer.
- Sale proceeds are not taxable to the seller, and the buyer's discount is not taxable income.
- Eleven federal tax credits are transferable; the OBBB set new deadlines for several and added PFE rules to six.
- Tax credit transfer volume reached $42.0 billion in 2025, and Crux forecasts it will reach $47.5–49.0 billion in 2026.
FAQs for transferable tax credit buyers
Who can buy transferable tax credits?
Any taxpayer with federal income tax liability that is unrelated to the seller can buy transferable tax credits. In practice, most buyers are corporations, and 21% of Fortune 1000 companies already participate. A few groups face limits:
- Individuals can buy tax credits, but passive activity rules generally let them apply tax credits only against tax on passive income, not wages or investment income.
- Closely held C corporations face similar rules, with some exceptions. They should confirm with tax counsel how much active income tax credits can offset.
- Partnerships can buy tax credits and allocate them to their partners.
- Specified foreign entities cannot buy tax credits subject to the PFE rules.
- Tax-exempt organizations cannot buy tax credits because they have no income tax liability to offset.
Some family offices and high-net-worth individuals that once invested in tax equity find tax credit purchases appealing because they can time payment closer to their filing date. Still, Crux expects corporations to remain the core of the buyer market.
How much do transferable tax credits cost?
Tax credits sell at a discount to face value, quoted in cents on the dollar. In H1 2026, ITCs averaged $0.913 and PTCs averaged $0.930, a few cents below their historical norms, according to Crux's 2026 Mid-Year Market Intelligence Report.
Prices reflect only tax credits that sold. A large pool of PFE-exposed tax credits remains unsold, so the discount needed to clear them may be wider.
What drives tax credit pricing?
- PFE exposure. This is now the biggest driver. Tax credits exempt from PFE rules sold at a premium of $0.015 for ITCs and $0.020 for PTCs in H1 2026.
- Seller credit quality. Investment-grade sellers earn higher prices because their indemnities are stronger. That premium narrowed to about $0.015 in 2026, from $0.030 in 2025.
- Tax credit type. PTCs usually price above ITCs because they carry no recapture risk. Legacy §45 PTCs sit at the top of the market.
- Deal size. Large deals attract more buyers and tighter pricing; small deals often need a deeper discount.
- Timing. Buyers who commit earlier in the year or sign forward commitments for future years can usually negotiate larger discounts.
- Documentation and insurance. Clean diligence files and insurance coverage support stronger pricing.
Read more: Factors that affect tax credit pricing.
How much can buyers save?
A buyer’s savings equal the discount. In this illustrative example, a hypothetical company with $20 million in federal tax liability buys $20 million of PTCs at the H1 2026 average price of $0.930:
Illustrative example only. Actual savings depend on price, transaction terms, and the buyer’s tax position.
The return is often higher than the discount suggests. Companies already set aside cash for quarterly estimated tax payments, and that cash usually earns nothing. Buying tax credits turns it into a return, especially when payment is timed to match the tax payment dates.
Sellers typically pay transaction costs such as intermediary fees and insurance, and often reimburse the buyer's legal costs up to a negotiated cap.
What is the process and timeline for buying tax credits?
A first purchase usually takes three to eight months from the start of internal approvals to funding, and requires about 20–40 hours of the buyer's internal time. Once approvals are in place, most Crux-facilitated deals move from credit search to funding in about three months.
The process has two phases that partly overlap, so total time is shorter than the sum of the steps:
When can buyers use purchased tax credits?
Buyers can use tax credits in the same tax year they are generated, and they can count planned purchases toward their quarterly estimated tax payments before any cash changes hands. Three timing rules shape every purchase:
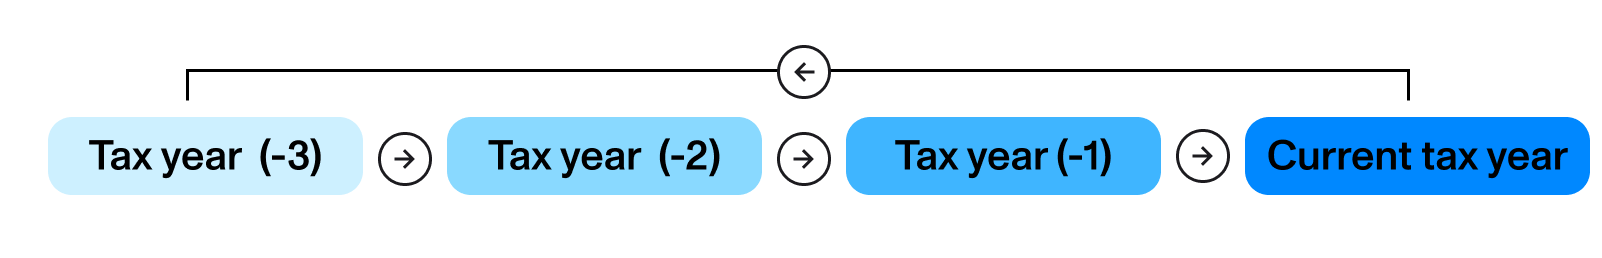
- The tax year follows the seller. Under Section 6418(d), a buyer claims a tax credit in its first tax year ending with or after the seller's tax year in which the tax credit was generated.
- The transfer must happen before either party files. Buyers can still purchase prior-year tax credits until their return is filed, including extensions. In H1 2026, 2025-vintage tax credits made up 32% of transfer volume.
- Registration takes time. The seller needs an IRS registration number before the returns are filed, and the IRS recommends allowing 120 days. Deals often fund before the number arrives, but buyers should confirm it will be ready in time.
What if the buyer and seller have different fiscal years?
Most large corporate taxpayers use a calendar year, but a mismatch can push tax credits into the buyer's next tax year:
How do buyers time payments?
Buyers usually choose one of four approaches, depending on whether they want the deepest discount or the smallest cash outlay:
- Pay as tax credits are generated. For PTCs and §45X tax credits, buyers commit to a year's volume and pay quarterly in arrears, timed to their estimated tax payment dates.
- Commit early, pay later. Buyers commit to ITCs early in the year, reduce their estimated payments, and pay when the project is placed in service. The risk is a project slipping into the next tax year, so agreements often include remedies for late delivery.
- Top up at year-end. Buyers wait until they know their full-year liability, then buy tax credits to offset the remaining Q4 or final payment.
- Buy prior-year tax credits. Buyers who finish their tax position late can still buy tax credits for the prior year before filing. One financial services firm secured $25 million in prior-year tax credits ahead of its filing deadline.
Read more: The corporate tax team’s guide to timing and executing tax credit purchases
What are the risks, and how do buyers protect themselves?
The buyer takes on the risk that the IRS later disallows, reduces, or recaptures a purchased tax credit. Buyers manage that risk with diligence, seller indemnities, and tax credit insurance, and serious problems are rare: 90% of buyers report no IRS contact on their tax credit purchases.
Risks by tax credit type
The core risks
- Eligibility risk: The project or bonus adders do not meet statutory requirements.
- Basis risk: The IRS reduces the cost basis an ITC is calculated on. Direct transfers are generally valued at cost, and the Alta Wind decision raised the bar for documenting any basis step-up.
- Placed-in-service risk: An ITC project enters service later than planned, shifting the tax credit into the next tax year.
- Recapture risk: An ITC project stops qualifying or changes ownership within five years of entering service. The amount at risk falls by 20% each year. PTCs are not subject to recapture once earned.
- Structural risk: Flaws in the seller's ownership chain or entity structure undermine its right to sell.
- Seller credit risk: A seller that cannot pay its indemnity, or abandons a project during the recapture period, leaves the buyer exposed.
- PFE risk: A project or seller fails the new foreign-entity rules. Most insurance policies currently exclude this risk, so buyers lean on investment-grade sellers and legal opinions.
- The excessive credit transfer penalty: If a buyer claims more than the seller actually had to sell, the buyer owes the difference plus a 20% penalty unless it shows reasonable cause. Relying on the seller's representations alone does not meet that standard, which is why thorough diligence matters.
How buyers protect themselves
Diligence. Buyer counsel confirms the project will enter service in the target tax year, validates its cost basis and value, and reviews core project documents and the seller's credit support. Crux's data room populates market-standard diligence checklists so counsel can request and review documents in one place.
Seller indemnities. The seller agrees to make the buyer whole if tax credits are disallowed or recaptured, usually backed by a parent guarantee. Most buyers seek coverage above face value. According to Crux’s 2026 Mid-Year Market Intelligence Report, 71% of deals with a quantified cap set it above 100% of the purchase price, to cover IRS interest, penalties, and contest costs. Change-in-tax-law provisions now appear in 55% of transfer agreements, up from 12% in H1 2024.
Tax credit insurance. A policy pays the buyer if the IRS disallows or recaptures covered tax credits and the seller cannot. Coverage of 90–140% of credit value is most common, and some deals reach 165%; coverage below 100% usually supplements a strong seller indemnity. The seller typically pays the premium, historically 2–5% of the insured amount, and a growing share of 2026 policies cost 5% or more. Buyers can also accept uninsured tax credits at a deeper discount.
Go deeper: A guide to the tax credit insurance market.
Go deeper: How the market manages tax credit loss, audit risk, and indemnities.
What corporate tax and accounting issues should buyers consider?
Large corporate buyers should check three minimum tax regimes and their financial reporting before sizing a purchase. Each can change how much value a tax credit delivers.
- Corporate alternative minimum tax (CAMT). CAMT sets a 15% minimum tax on adjusted financial statement income for the largest corporations. Purchased tax credits reduce regular tax, but the minimum can limit how much they lower a buyer's total bill. The price paid and the discount are both excluded from that income calculation.
- Base erosion and anti-abuse tax (BEAT). BEAT applies to large multinationals that make significant payments to foreign affiliates. Legacy §45 and §48 tax credits receive more favorable treatment under BEAT than §45Y, §48E, and other tax credits, so buyers subject to BEAT often prefer them.
- Pillar Two. The OECD's global minimum tax treats purchased tax credits favorably, and 2026 developments exempted most US-parented groups. Foreign-parented buyers should still confirm their exposure.
How do buyers account for purchased tax credits?
Under US generally accepted accounting principles (GAAP), buyers account for purchased tax credits under ASC 740, the income tax standard. In most cases, a buyer:
- Records a deferred tax asset for the full amount of tax credits purchased, and a deferred credit for the discount.
- Recognizes the discount as an income tax benefit as the tax credits are used on its tax returns.
- Either adds transaction costs to the purchase price or expenses them, depending on its accounting policy.
- Generally expenses insurance premiums it pays when the policy is bound, and records any insurance or indemnity recovery separately from the tax provision.
Because audit committees often sign off on a first purchase, buyers should loop in their auditors early.
Read more: Accounting lessons and FAQs for tax credit buyers.
Can tax credits be carried forward or back?
Yes. Under Section 39, buyers can carry unused purchased tax credits back three years and forward 22 years. Because a buyer cannot resell tax credits, carryovers are the only way to use credits that exceed a year's liability.
Carrying credits forward is straightforward. Carrybacks follow a set order:
- Unused tax credits apply first to the earliest year in the carryback period, three years before the current year.
- Any remainder then applies to the following year, and finally to the prior year.
- Each carryback requires amending a return that has already been filed.
Ready to buy tax credits?
Whether you’re planning purchases early in the year or offsetting your final tax bill at year-end, Crux's tax investor team can source vetted, underwritten tax credits that match your timing, pricing, and risk preferences, and support you from term sheet to funding.
Talk to the Crux team about buying tax credits.
Key takeaways for buyers
- Most corporate taxpayers can buy tax credits; individuals can too, but passive activity rules limit their use.
- In H1 2026, ITCs averaged $0.913 and PTCs averaged $0.930 per $1.000 of tax credit. PFE exposure is now the biggest driver of price.
- A tax credit purchase takes three to eight months including internal approvals, and about 20–40 hours of the buyer's time.
- Buyers can count planned purchases toward estimated tax payments and time payments to avoid going out of pocket.
- Diligence, seller indemnities, parent guarantees, and tax credit insurance protect buyers against disallowance and recapture.
- Unused tax credits can be carried back three years and forward 22 years.
Learn more: The corporate tax team's guide to transferable tax credits.
FAQs for transferable tax credit sellers
What are tax credit buyers looking for?
Buyers want tax credits they can count on, delivered when they need them. Most time purchases around their quarterly estimated tax payments, which gives the market a seasonal rhythm. In 2026, buyers rank these factors highest:
- No PFE exposure, or clear evidence of compliance. This is now the biggest driver of buyer demand and price.
- A creditworthy seller. Investment-grade sellers, or sellers with a strong parent guarantee, attract more bids.
- Complete documentation. Organized diligence files shorten timelines and support stronger pricing.
- Insurance. A policy covering eligibility, basis, and recapture risk reassures buyers, especially for ITCs.
- Clear IRS compliance. That includes timely registration and prevailing wage and apprenticeship (PWA) records.
- Timing that fits the buyer's tax calendar. Tax credits available when buyers make estimated payments sell more easily.
Read more: Tips to make your tax credits more transactable.
What steps does a seller take to transfer tax credits?
The basic transfer mechanics are covered above. These are the steps sellers own, which do not have to happen in this exact order:
- Confirm eligibility. Most for-profit taxpayers can transfer tax credits. Tax-exempt organizations, governments, and rural electric cooperatives generally use elective pay instead.
- Build a qualifying project. It must meet every statutory requirement, including beginning-of-construction deadlines, placed-in-service dates, PFE rules, and the requirements for any bonus credits claimed.
- Register each facility with the IRS. Sellers submit one registration request per tax year through the IRS pre-filing registration portal, and receive a separate registration number for each facility. The IRS recommends allowing 120 days.
- Sign the transfer election statement. The seller and buyer sign it once the deal is done. The transfer must happen before either party files its return for that year, and the election cannot be revoked.
- File the return. The seller reports the transfer on its return for the year the tax credit was generated, including registration numbers, by the due date including extensions.
- Renew registrations every year. PTC sellers transferring tax credits across multiple years must renew registration and file each year.
Timelines depend on documentation readiness. Sellers with organized, PWA-compliant files move faster, and Crux's suite of automated diligence tools help them get there.
Read more: 4 ways developers can prepare to sell smaller tax credits.
What are the beginning-of-construction rules for wind and solar?
Under the OBBB, wind and solar projects claiming §48E or §45Y must begin construction by July 4, 2026, or be placed in service by the end of 2027. Projects that met the July 4 deadline generally have four years to be placed in service. Storage, nuclear, geothermal, and other technologies face later phase-downs.
Developers can show construction began in two ways:
- The physical work test: Significant physical work of a substantial nature has begun on site or off site, such as manufacturing custom components under a binding contract.
- The 5% safe harbor: The developer has paid or incurred at least 5% of the project's total cost.
In August 2025, IRS Notice 2025-42 eliminated the 5% safe harbor for most wind and solar projects. On June 6, 2026, a federal court vacated that notice, restoring the 5% safe harbor just 27 days before the deadline.
Few developers changed course that late, and an appeal remains possible. Buyers, investors, and lenders are likely to discount tax credits from projects that rely only on the reopened safe harbor until the legal question settles. Crux estimates more than 170 GW of wind and solar capacity was safe-harbored before the deadline, which will support tax credit supply for years.
What bonus tax credits are available, and who qualifies?
Bonus tax credits, often called adders, raise the value of a base tax credit when a project meets labor, sourcing, or location requirements. Stacked together, they can lift an ITC from a 6% base to 50% of eligible cost, or up to 70% with a low-income allocation.
Prevailing wage and apprenticeship
The PWA bonus multiplies the base credit by five. Projects must pay prevailing wages during construction and for any later repairs or alterations: for five years after an ITC project is placed in service, or for the full 10-year credit period of a PTC project. They must also use registered apprentices for a share of construction labor hours. Projects that began construction before Jan. 29, 2023, or that are smaller than 1 MW are exempt. Buyers now treat PWA compliance as the baseline when valuing tax credits.
Read more about IRS guidance on PWA requirements.
Domestic content
Projects must use 100% US-made steel and iron for structural components, plus a minimum share of US-made manufactured products. That share rises with the year construction begins: 40.0% for projects that began construction before June 16, 2025, 45.0% for the rest of 2025 (27.5% for offshore wind), 50.0% in 2026 (35.0% for offshore wind), and 55.0% from 2027. For a PWA-compliant project, the bonus raises an ITC from 30% to 40%, or increases a PTC by 10%.
Read more about the domestic content safe harbor.
Energy communities
Projects in an energy community earn a bonus. For an ITC, the credit rate rises by 10 percentage points, from 30% to 40% of eligible costs for a PWA-compliant project. For a PTC, the credit amount rises by 10%. There are three ways to qualify:
- Brownfield sites, as defined under federal environmental cleanup law.
- Fossil fuel employment areas: Metropolitan or nonmetropolitan areas where coal, oil, or natural gas once supplied at least 0.17% of direct employment or 25.0% of local tax revenue, and where unemployment is at or above the national average.
- Coal closure areas: Census tracts, or adjoining tracts, where a coal mine closed after 1999 or a coal-fired power plant retired after 2009.
The OBBB added a similar bonus for advanced nuclear facilities in areas with significant nuclear industry employment.
Low-income communities
The low-income bonus is awarded through an annual allocation, not claimed automatically. Solar and wind projects smaller than 5 MW can apply for 10 extra percentage points if located in a low-income community or on tribal land, or 20 percentage points if they serve a qualified low-income residential building or economic benefit project.
Read more about the low-income communities bonus.
Can bonus credits be sold separately?
No. Sellers cannot sell bonus credits on their own. Each transfer must include a proportional slice of the base credit and every bonus, so a buyer purchasing 25% of a project's tax credits receives 25% of each component. If a bonus is later disallowed, the buyer bears its share of the loss, which is why buyers diligence bonus credits as closely as base credits.
What does a seller net after fees and costs?
Sellers usually net $0.03–0.06 less than the gross price per dollar of tax credit. They typically pay these costs:
- Tax credit insurance: Historically 2–5% of the insured amount, depending on deal size and risk. A growing share of 2026 policies cost 5% or more.
- Intermediary fees: Usually 0.5–3.0% of the tax credit value.
- The buyer's diligence and legal costs: Reimbursed up to a negotiated cap.
- The seller's own costs: Legal counsel, plus any appraisal or cost segregation report needed to support eligibility.
Here is an illustrative example of a $20 million ITC sale at the H1 2026 average price. The fees and costs are assumptions within typical market ranges, not quotes:
Illustrative example: seller net proceeds
The seller's own legal, appraisal, and cost segregation costs come out of that figure too. Read more: Tax credit insurance coverage, cost, and how to procure it.
Transferability vs. tax equity: Which structure fits?
Transferability did not replace tax equity; the two increasingly work together. Hybrid structures, which pair a tax equity partnership with a tax credit sale, made up $28.8 billion of tax equity volume in H1 2026. Crux expects total tax equity and preferred equity investment to reach $46.3 billion in 2026, up 17% from 2025, with about 70 providers in the market, up from roughly 25 in 2022.
Traditional tax equity usually has the lowest cost of capital, hybrid structures price slightly higher, and preferred equity prices highest but offers the most flexibility. Preferred equity is the fastest-growing segment: Crux projects $7.45 billion in 2026 tax credits sold out of preferred equity structures, more than double the 2025 total.
When might tax equity be the better choice?
- Depreciation matters. Accelerated depreciation, known as MACRS, cannot be transferred. If a sponsor cannot use it, a tax equity partner can.
- A basis step-up is available. Selling a project into a partnership at fair market value can raise the cost basis an ITC is calculated on. Direct transfers are generally valued at cost. After the Alta Wind decision, step-ups need appraisals anchored in comparable market data. Fewer than 5% of deals by value report step-ups above 30%.
- The project is large and complex. Tax equity takes longer, often 6 to 12 months, but can deliver more total value on big projects.
For most mid-size projects and manufacturers, a direct transfer is faster, cheaper, and easier to access. Tax equity isn’t available for every project type: investors have historically focused on large wind and solar projects, and many have been cautious about tech-neutral §48E and §45Y projects because of PFE risk. That caution is easing as investors become more comfortable pricing and diligencing PFE exposure, even without full Treasury guidance. Preferred equity can also fill the gap, because preferred equity investors take smaller ownership stakes and are less exposed to PFE risk.
Read more: The ultimate guide to tax equity and clean energy tax credits.
Crux's capital markets team helps sponsors raise tax equity and preferred equity alongside tax credit sales.
Read more: Tax equity structures and deal terms, with White & Case.
When is a transferable tax credit generated?
The answer depends on the tax credit type, and it determines when a seller can sell and when a buyer can use the tax credit:
- ITCs are generated in full when a project is placed in service. Projects with long construction periods may claim partial tax credits for qualified progress expenditures along the way, but those cannot be transferred. Only the ITC generated in the placed-in-service year can be sold.
- Electricity PTCs (§45 and §45Y) are generated for each megawatt-hour produced and sold over a 10-year period after the project enters service.
- Manufacturing PTCs (§45X) are generated when an eligible component is sold.
- Clean fuel PTCs (§45Z) are generated when qualifying fuel is produced and sold, through 2029.
What are PTC strips and spot sales?
PTC sellers can sell in two ways:
- Forward sales, or strips: The seller commits a stream of future PTCs, typically several years' worth, to one buyer. Sellers usually commit a conservative estimate of production so they do not fall short in a weak year.
- Spot sales: The seller sells PTCs already generated, or any production above its forward commitment. Spot PTCs must be sold before the seller files its return for that year, including extensions.
Strip sales fell sharply in 2026, to $1.0 billion in H1 from $8.8 billion a year earlier, as last year's burst of large multi-year deals faded. Buyers still prefer to commit near the end of their tax year, when their liability is clearer, so sellers with flexible delivery timing often find more demand.
Is bridge financing available?
Yes. Bridge loans let developers and manufacturers borrow against expected tax credit or tax equity proceeds, so they can fund construction before the tax credits are generated and sold. Tax credit and tax equity bridge loans reached $12 billion in H1 2026, up 10% from H2 2025, making them the fastest-growing category of clean energy debt. Pricing held broadly stable.
Lenders typically want a forward commitment from a tax credit buyer or tax equity investor before funding, because that commitment repays the loan. Pricing and terms also depend on:
- The sponsor's creditworthiness
- Documentation quality
- Credit enhancements such as tax credit insurance
Crux connects sponsors with active lenders across bridge, construction, and term debt, and helps coordinate debt with tax credit sales.
Read more: Key criteria lenders use to evaluate clean energy deals.
Ready to sell tax credits?
Crux's team helps developers and manufacturers raise capital across the full capital stack, from tax credit sales and hybrid tax equity to preferred equity and bridge loans. Our experienced deal team, proprietary market data, and deep pool of transaction-ready buyers help secure the right capital with greater certainty.
Talk to the Crux team about selling tax credits.
Key takeaways for tax credit sellers
- Sellers must confirm eligibility, register each facility with the IRS, and sign a transfer election statement before either party files its return.
- Wind and solar projects needed to begin construction by July 4, 2026 or be placed in service by Dec. 31, 2027; a June court ruling restored the 5% safe harbor, but buyers may discount tax credits that rely on it alone.
- Stacked bonus credits can lift an ITC from a 6% base to 50%, and buyers receive a proportional share of every bonus.
- Insurance (historically 2–5% of the insured amount, often 5% or more in 2026), intermediary fees (0.5–3.0%), and legal and diligence costs typically leave sellers $0.03–0.06 below the gross price.
- Tax equity still wins when depreciation or a basis step-up adds value, and hybrid structures now dominate the tax equity market.
- Bridge loans against future tax credit proceeds grew to $12 billion in H1 2026.
See how Palmetto used tax credit sales to scale its business.
Glossary: Transferable tax credits
Adder (bonus tax credit). A statutory bonus that increases the base value of a federal clean energy tax credit when the project meets a specified condition (such as paying prevailing wages, using domestic content, or being located in an energy community). Multiple adders may be stacked on a single project.
Basis (eligible basis). The cost basis of qualifying property on which an investment tax credit (ITC) is calculated. For credits transferred under §6418, basis is generally the project's actual cost — not a stepped-up fair market value.
Beginning of construction (BoC). The IRS-defined date on which a project is treated as having started construction for tax credit purposes. BoC can be established by either a physical-work test or a 5% safe-harbor test, and a project must demonstrate continuous progress toward completion afterward.
Bridge loan (tax credit bridge financing). A short-term loan secured by a developer's or manufacturer's expected proceeds from a future transferable tax credit sale. Bridge loans typically require a forward credit purchase commitment from a creditworthy buyer as the repayment source.
Brownfield site. A site contaminated or potentially contaminated by hazardous substances, pollutants, or contaminants, as defined under CERCLA. Projects located on brownfield sites can qualify for the energy community adder.
Carryback and carryforward. Rules that let a buyer apply unused tax credits to other tax years. Under Section 39, purchased tax credits can be carried back three years, starting with the earliest year, or forward 22 years. Carrybacks require amending previously filed returns.
Cost segregation report. An engineering-led analysis that allocates a project's total cost across eligible and ineligible categories for tax credit purposes. Cost segregation supports ITC valuation and is a standard diligence document in transferable credit transactions.
Domestic content bonus. A bonus worth 10 extra percentage points on an ITC, or 10% more on a PTC, for projects built with US-made steel and iron and a minimum share of US-made manufactured products. That share depends on when construction begins: 40% for projects that began construction before June 16, 2025, 45% for the rest of 2025, 50% in 2026, and 55% from 2027. Available for §45, §48, §45Y, and §48E.
Elective pay. A Section 6417 option that lets tax-exempt organizations, governments, and rural electric cooperatives receive certain tax credits as a cash payment from the IRS instead of selling them. Some for-profit taxpayers can also use it for §45Q, §45V, and §45X tax credits for a limited period. Also called direct pay.
Energy community adder. A federal tax credit bonus of 10 percentage points (ITC) or 10% (PTC) for projects located in (a) a brownfield site, (b) a metropolitan or non-metropolitan statistical area with significant historical fossil-fuel employment or tax revenue and elevated unemployment, or (c) a census tract with a recently closed coal mine or retired coal-fired electric generating unit.
Engineering, procurement, and construction (EPC) agreement. The contract between a project developer and the firm responsible for building the project. The EPC agreement is a standard diligence document used to validate project cost and scope in transferable credit transactions.
Federal tax credit. A direct reduction of federal income tax liability, dollar-for-dollar. Federal clean energy and manufacturing tax credits include the §45 PTC, §48 ITC, §45Q, §45U, §45V, §45X, §45Y, §45Z, §48C, §48E, and others.
Foreign entity of concern (FEOC). The earlier term for foreign-ownership restrictions on energy tax credits. The OBBB replaced it with the prohibited foreign entity rules. See Prohibited foreign entity.
Indemnity. A contractual promise by a credit seller to make a credit buyer whole if a transferred credit is later disallowed, recaptured, or reduced. Indemnities are typically backed by a parent guarantee, a tax insurance policy, or both.
Inflation Reduction Act (IRA). The 2022 federal statute that established or expanded most of the federal clean energy and manufacturing tax credits, and that enacted IRC §6418 (transferability) and §6417 (elective payment).
Investment tax credit (ITC). A one-time federal tax credit calculated as a percentage of an eligible project's cost basis, claimed in the year the project is placed in service. Codified at §48 (pre-2025 construction start) and §48E (post-2025 construction start).
IRC §6418. The Internal Revenue Code section, enacted in the 2022 IRA, that authorizes the one-time transfer of certain federal clean energy and manufacturing tax credits from an eligible taxpayer to an unrelated taxpayer for cash.
Low-income community bonus. A federal tax credit bonus available to small solar and wind facilities (under 5 MW AC) located in a qualifying low-income community, in connection with a qualified low-income residential building project, or as part of a qualified low-income economic benefit project. The bonus is 10 or 20 percentage points and is allocated annually by Treasury.
MACRS (modified accelerated cost recovery system). The federal depreciation regime that allows clean energy property to be depreciated on an accelerated schedule (typically 5-year). MACRS depreciation cannot be transferred under §6418 — it remains with the project owner — which is one reason tax equity remains preferred for projects where depreciation is a material share of total benefits.
Make-whole provision. An indemnity term obligating the credit seller to compensate the buyer for the full economic loss — typically including taxes, interest, and penalties — if a transferred credit is later disallowed or recaptured.
One Big Beautiful Bill (OBBB). The 2025 federal statute that modified many IRA-era clean energy and manufacturing tax credits, including phaseout schedules for wind and solar credits, the addition of prohibited foreign entity (PFE) rules, and the extension of certain credits (such as §45Z through 2029).
Parent guarantee. A credit support mechanism in which the parent company of a credit seller agrees to backstop the seller's indemnities. Parent guarantees are typically used by investment-grade sellers in lieu of tax insurance.
Passive activity. Under US tax law, an income- or loss-producing activity in which the taxpayer does not materially participate. Individual buyers of transferable tax credits are subject to passive activity rules: a credit's face value can generally only be applied against tax liability from passive, non-investment income.
Placed in service. The date a project is ready and available for its intended use. Placed-in-service date triggers ITC eligibility and starts the five-year recapture period.
Pre-filing registration. The IRS process a seller completes before transferring tax credits. The seller submits one request per tax year through the IRS online portal and receives a registration number for each facility, which must appear on the transfer election statement and both parties' returns. The IRS recommends allowing 120 days. PTC sellers renew each year. Deals can be signed and funded before the number arrives.
Prevailing wage and apprenticeship (PWA). A set of federal labor standards that, when met during a project's construction and continued for the credit's recapture or production period, multiply the base ITC or PTC rate by 5×. PWA compliance is now the baseline assumption for credit valuation in most clean energy transactions.
Production tax credit (PTC). A federal tax credit earned per unit of qualifying output (e.g., per kWh of electricity, per kg of hydrogen, per gallon of clean fuel, per component manufactured), claimed each year for a defined period after the project enters service. Codified at §45 (pre-2025 construction), §45Y (post-2025 construction), §45Q, §45U, §45V, §45X, and §45Z, among others.
Prohibited foreign entity (PFE). A category created by the OBBB that covers specified foreign entities and foreign-influenced entities tied to China, Russia, North Korea, or Iran, through ownership, effective control, or certain payments. PFE rules apply to §48E, §45Y, §45X, §45U, §45Z, and §45Q. They limit who can claim those tax credits and how much material assistance a project or component can receive from PFEs. Those tax credits also cannot be sold to a specified foreign entity. Legacy §45 and §48 tax credits are exempt.
Recapture. The IRS's right to reclaim part of an ITC if the project stops qualifying, or is sold or abandoned, within five years of being placed in service. The amount at risk falls by 20% each year, from 100% in year one to 20% in year five. In a transfer, the buyer bears the recapture liability and relies on seller indemnities and insurance for protection. PTCs are not subject to recapture once earned.
Recapture period. The five-year period following an ITC project's placed-in-service date during which the project must remain in qualifying use. The recapture risk to the buyer steps down 20 percentage points per year.
Registration number. The unique identifier issued by the IRS at the end of the pre-filing registration process. The registration number must appear on the transfer election statement and on both parties' tax returns for each transferred credit.
Safe harbor (beginning of construction). A method for proving a project began construction by a deadline. Developers can use the physical work test, or the 5% safe harbor by paying or incurring at least 5% of the project's total cost. IRS Notice 2025-42 eliminated the 5% safe harbor for most wind and solar projects, but a federal court vacated that notice on June 6, 2026, restoring it. An appeal remains possible.
Step-up in basis. An increase in the tax basis of project assets from cost to fair market value, achievable under a tax equity partnership structure. A step-up can increase the size of the ITC relative to a cost-basis calculation, but is not available in direct §6418 credit transfers.
Strip (tax credit strip). A multi-year forward commitment from a buyer to purchase a defined volume of future PTCs from a project. Strips are most common in §45 / §45Y wind and solar PTC transactions but are also used for §45X (typically in 2–3 year strips) and §45U (typically 1-year tranches).
T-flip (transferability + tax equity hybrid). A hybrid project finance structure that pairs a traditional tax equity partnership — which captures depreciation and, where available, a step-up in basis — with a transfer of the credit itself to a third-party buyer under §6418. T-flips are increasingly used by large sponsors that want to combine tax equity economics with the broader buyer pool transferability unlocks.
Tax credit insurance. A policy that pays a tax credit buyer if the IRS disallows or recaptures covered tax credits and the seller cannot. It typically covers eligibility, basis, and recapture risk at 90–140% of credit value. Sellers usually pay the premium, historically 2–5% of the insured amount, and often 5% or more in 2026. Most policies currently exclude PFE risk.
Tax credit transfer agreement (formerly known as purchase and sale agreement (PSA)). The principal commercial contract between a credit buyer and seller in a transferable tax credit transaction. The tax credit transfer agreement documents purchase price, payment terms, representations and warranties, indemnities, and conditions precedent to funding.
Tax equity. A project finance structure in which an institutional investor enters a partnership with the project sponsor and receives a special allocation of tax credits, depreciation, and cash distributions in exchange for upfront capital. Tax equity is the foundational structure that has financed the majority of US utility-scale renewables; transferability is a complementary path that broadens access.
Term sheet. A non-binding written summary of the principal commercial terms of a proposed tax credit transaction, used to align buyer and seller before tax credit transfer agreement drafting. Legal-fee reimbursement provisions in a term sheet are typically binding even when the rest is not.
Transfer election statement. The IRS-required statement attached to both the seller's and buyer's tax returns documenting a credit transfer under §6418. The transfer election must occur before either party files the relevant return.
Transferability. The legal mechanism, established by IRC §6418, that permits a one-time sale of certain federal clean energy and manufacturing tax credits from an eligible taxpayer to an unrelated taxpayer for cash. Transferability is distinct from direct pay (which provides a cash refund from the IRS) and from tax equity (which uses a partnership structure).
Transferable tax credit. A federal energy or manufacturing tax credit that an eligible taxpayer can sell once, for cash, to an unrelated buyer under Section 6418. Eleven tax credits are transferable: §30C, §45, §45Q, §45U, §45V, §45X, §45Y, §45Z, §48, §48C, and §48E.